

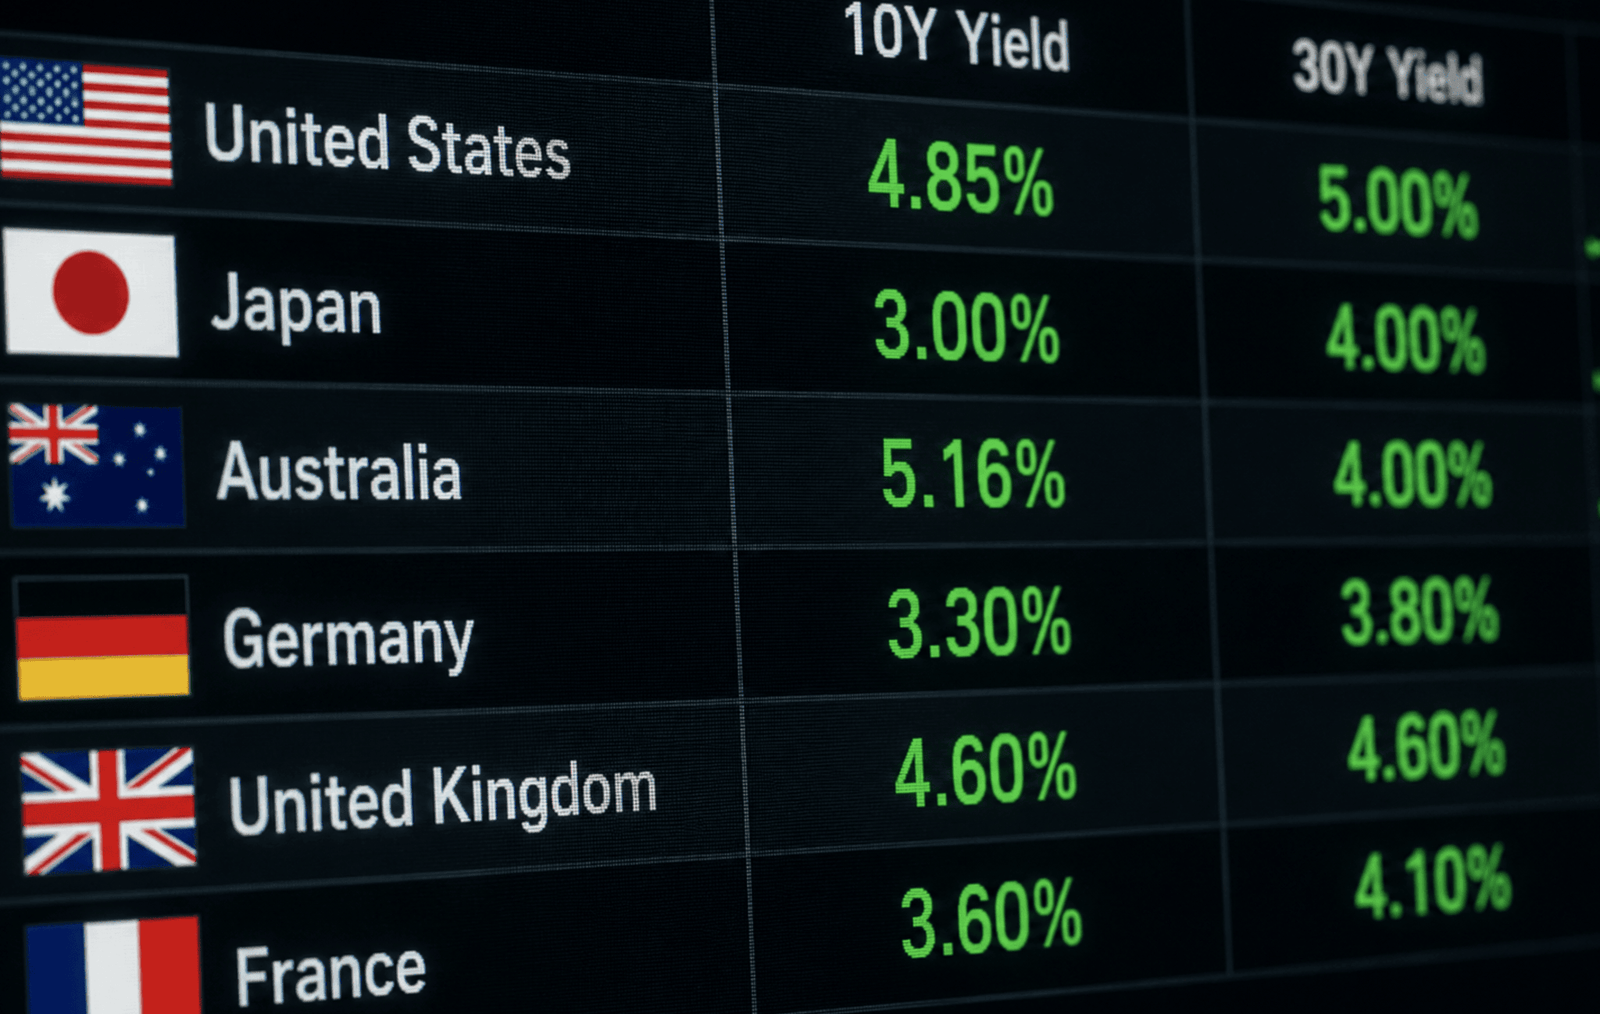
Something unusual is happening in global bond markets, and it is more consequential than the usual swings in yields. Government borrowing costs are rising across much of the developed world. The US 10-year Treasury is approaching 5 percent, and the 30-year Treasury yield is at levels not seen since 2007. “Meltdown” is too dramatic a word, but the bond market is clearly sending a message. Bond prices fall when investors demand higher yields, and global investors clearly want to be paid more for lending money to governments carrying large debts, running persistent deficits, and still contending with above-target inflation.
Japan is perhaps the most striking case. Its 10-year government bond yield has moved through 3 percent after spending most of a generation near zero, and its 30-year borrowing cost has risen above 4 percent — a multi-decade high. Australia’s 10-year recently reached 5.16 percent. Germany’s 10-year Bund has been trading around 3.3 percent, with the 30-year above 3.8 percent. Britain, France, and other developed economies are seeing versions of the same thing. The particulars differ from country to country, but the direction does not.
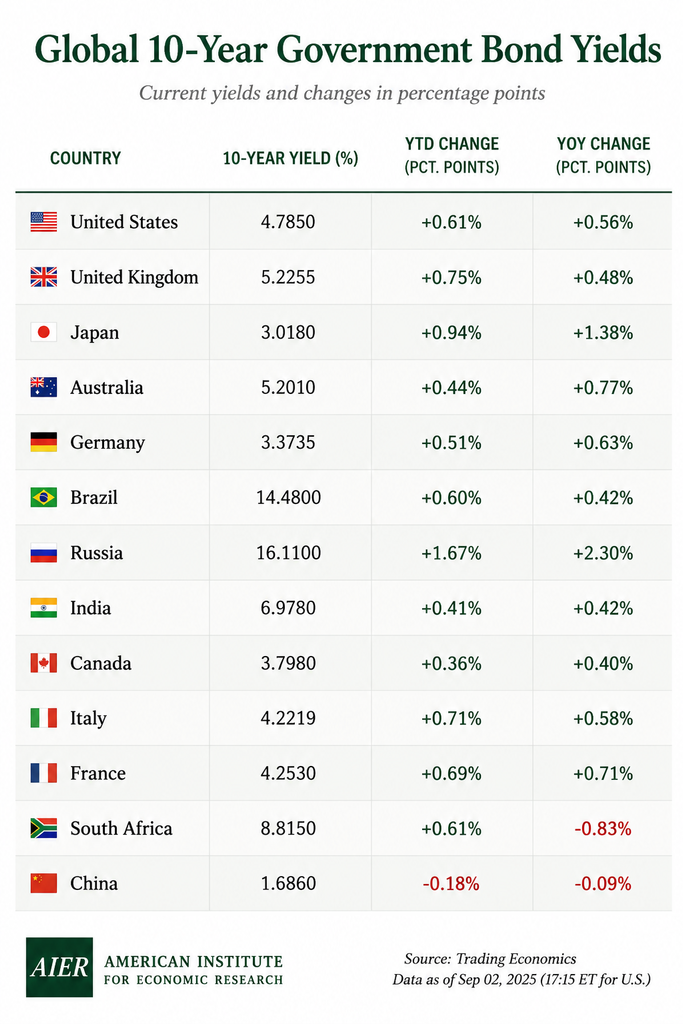
Oil prices and renewed inflation worries are part of the explanation, as is the growing possibility that central banks will have to keep monetary policy restrictive for longer than markets have expected. But these are proximate causes. The bigger story began several years ago. Governments entered the COVID period already heavily indebted, then responded to the pandemic with enormous fiscal programs supported by extraordinarily easy monetary policy. Central banks subsequently discovered that the resulting inflation was neither especially transitory nor easy to eradicate. Now, the consequently larger debts have to be financed and refinanced in markets where investors once again demand compensation for inflation, duration, and fiscal risk.
For the United States, the arithmetic becomes daunting fairly quickly. Gross federal debt recently passed $40 trillion, with roughly $32.3 trillion held by the public. The weighted-average maturity of marketable Treasury debt is about 71 months, although roughly one-third matures within the next year. So a 20-basis-point increase in the 10-year Treasury does not suddenly reprice $32 trillion of debt. But the government does not get to ignore higher rates, either. Something on the order of $10 trillion of marketable debt must roll over within a year. Meanwhile, Washington continues to borrow hundreds of billions more to finance new deficits.
A household analogy is useful here, with one qualification. Imagine an enormous mortgage that resets in pieces rather than all at once. A homeowner with a fixed-rate mortgage does not care very much if mortgage rates jump tomorrow: he cares about when he has to refinance. The US Treasury is constantly refinancing: some portion of the federal government’s enormous mortgage matures every day.
We can already see that process in the numbers. The average interest rate on interest-bearing Treasury debt was about 3.32 percent in January. By July it was roughly 3.45 percent. Thirteen basis points sounds like market noise, until the principal involved is measured in tens of trillions of dollars.
Using $32.3 trillion of publicly held debt as a rough base, every sustained 5-basis-point increase in the government’s average financing cost eventually means about $16 billion more in annual interest expense. Ten basis points means roughly $32 billion; 25 basis points, $81 billion; 50 basis points, $161 billion. A full percentage point works out to approximately $323 billion per year — about what the US spends on veterans’ support. Those are steady-state figures, not next-year budget estimates, because the existing debt has to reprice first. If roughly one-third of the debt rolls over within twelve months, a 10-basis-point increase would initially add something closer to $10–11 billion to the annual cost of the existing debt, before considering new borrowing.
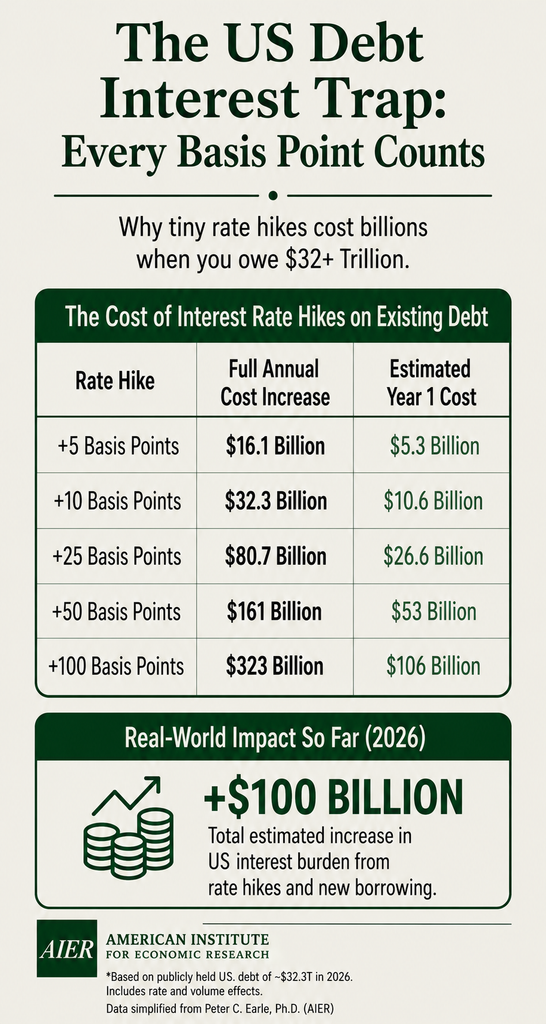
The change since January gives some idea of the scale involved. If the 13-basis-point increase in the US Treasury’s average interest rate were eventually reflected across today’s publicly held debt, the annualized increase would be around $42 billion. But the interest rate is only half of the problem: publicly held US Treasury debt has itself grown by roughly $2 trillion. Financing that additional principal at around 3.5 percent adds another $65–70 billion annually. Put the two together and the increase in the annualized interest burden is plausibly already in the neighborhood of $100 billion. That is a run-rate calculation, not a claim about actual fiscal-year outlays, but it illustrates what happens when both the amount borrowed and the price of borrowing rise together.
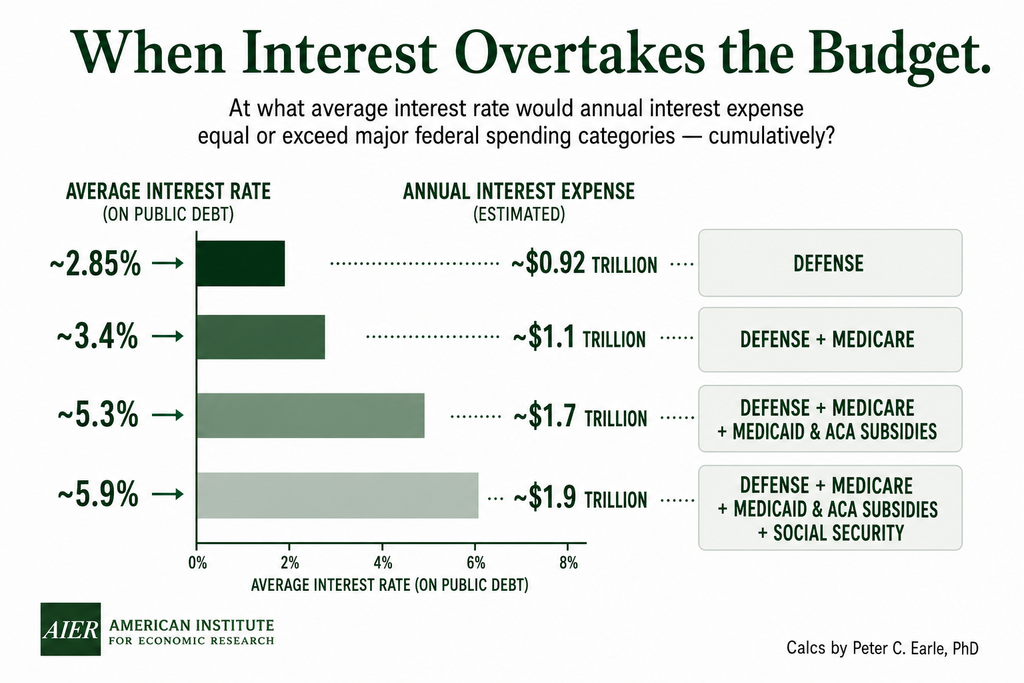
The budget implications are no longer theoretical. The US Congressional Budget Office (CBO) projects net federal interest expense above $1 trillion in fiscal 2026, against roughly $898 billion of defense spending. In other words, interest has already become larger than the defense budget. Medicare is roughly $1.1 trillion and Social Security around $1.7 trillion, with Medicaid and ACA subsidies representing another substantial expenditure.
There is another way to visualize the problem. Using the same $32.3 trillion debt base and deliberately simplified arithmetic, an average financing cost around 2.85 percent produces an interest bill roughly comparable with defense spending. Raise the effective financing cost and the interest burden becomes comparable with progressively larger combinations of defense, Medicare, Medicaid, and ACA subsidies, and eventually Social Security. This is an illustration, not a forecast: Treasury debt matures at different times, inflation-linked securities complicate the calculation, the government receives some interest income, and the debt stock will not remain at $32.3 trillion. But none of those qualifications changes the basic point: with this much debt outstanding, surprisingly small movements in average financing costs translate into very large amounts of money.
That is what makes the present bond selloff, and consequent rise in yields, significant. For years, developed-world governments operated as though enormous debt stocks and negligible financing costs could coexist more or less indefinitely. COVID pushed that experiment much further. And with the return of persistent inflation, the price of money changed.
Bond markets are now forcing governments to confront the change in circumstances. Yesterday’s deficit does not disappear when the fiscal year ends; it becomes part of the debt that has to be serviced tomorrow. Rising yields therefore work much like higher mortgage or credit card rates, except that governments are refinancing obligations measured in trillions. As more debt rolls over, the consequences migrate from trading screens into national budgets. Money spent servicing the debt is money that cannot be spent on defense, infrastructure, health care or Social Security without some combination of raising taxes, borrowing still more, or engaging in financial parlor tricks. At some point, the bond market stops offering commentary on fiscal policy choices and starts imposing limits. We appear to be approaching, if not at the early stages, of that phase.
